7 Mistakes You’re Making with Your Roof Insurance Claim (And How to Fix Them)
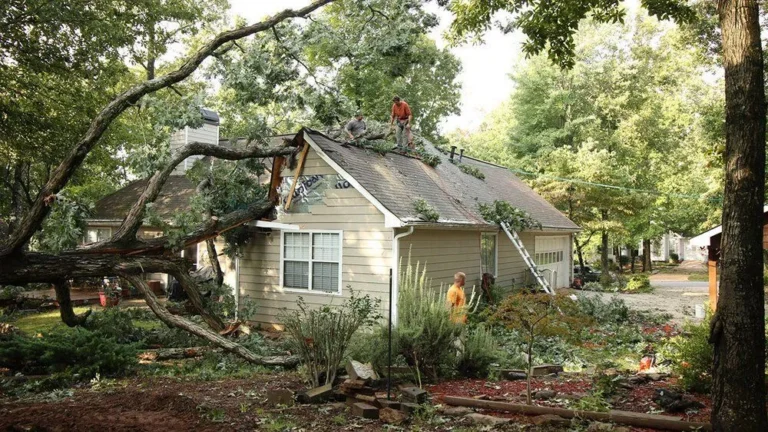
Living in the Dallas-Fort Worth area means dealing with a specific set of weather challenges. From the sudden, violent hail storms in the spring to the high-wind gusts that sweep through North Texas in the fall, our roofs take a beating. When the inevitable happens and a storm leaves your home vulnerable, the first instinct for many homeowners is to pick up the phone and call their insurance company.
While filing a claim is the right move, the process is often far more complex than it appears on the surface. Navigating the world of deductibles, depreciated values, and adjuster meetings can feel like learning a second language. Unfortunately, making even a small mistake early in the process can lead to a denied claim or a settlement that doesn't even cover the cost of the materials, let alone the labor.
At Texas Best Roofing Solutions, we see these hurdles every day. Our owner, Stan Short, previously worked as a licensed insurance adjuster. We document roof conditions and explain roofing findings clearly. We’ve identified seven of the most common mistakes DFW homeowners make during the roof insurance claim process and, more importantly, how you can avoid them to ensure your home is properly protected.
1. Failing to Document Damage Immediately
One of the biggest hurdles to a successful claim is a lack of evidence. Insurance companies rely on proof that a specific event: like a hailstorm or a high-wind event: caused the damage to your roof. If you wait several weeks to document the damage, it becomes much harder to prove that the issues weren't caused by general wear and tear or a different, older storm.
The Fix: As soon as it is safe to do so after a storm, take a walk around your property. You don't need to get on the roof yourself: in fact, we recommend staying on the ground for safety. Use your phone to take high-resolution photos of your yard, any downed tree limbs, dented gutters, or shingles that have blown off. If you see water spots on your ceiling inside, document those immediately.
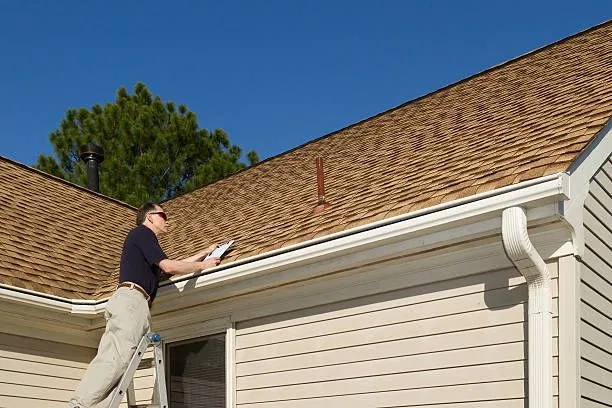
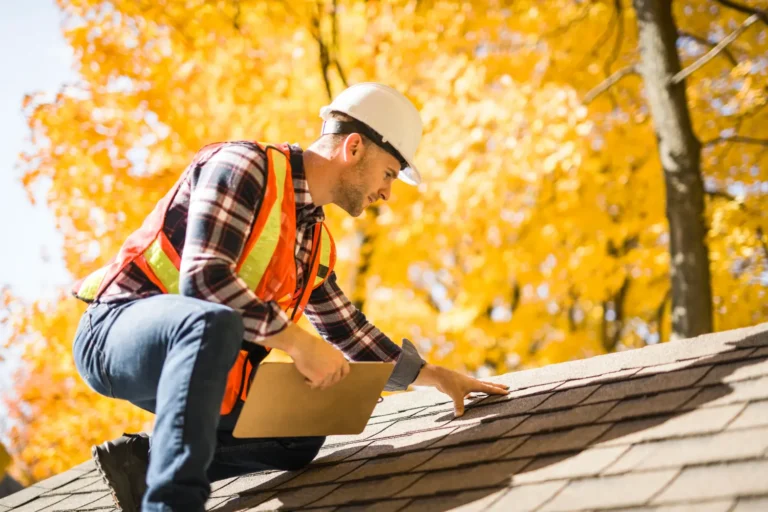
Better yet, schedule a free roof inspection. Our team can provide professional documentation that adjusters find much more difficult to dispute.
2. Filing a Claim Without Understanding Your Policy
Not all insurance policies are created equal. In Texas, many homeowners are surprised to find out their policy has changed over the years. Some policies offer Replacement Cost Value (RCV), which covers the full cost of replacing your roof at today’s prices. Others offer Actual Cash Value (ACV), which only pays out the depreciated value of the roof based on its age.
The Mistake: Filing a claim for a total replacement when your policy only covers ACV for an 18-year-old roof can lead to a financial "gap" that you aren't prepared to pay out of pocket.
The Fix: Before you even call your agent, you should have a clear understanding of your coverage. This is where our unique background comes in. We offer conducted by our staff's former licensed insurance adjuster. We can help you identify your deductible (which is often a percentage of your home's value in DFW) and explain exactly what your insurance company is obligated to pay.

3. Waiting Too Long to Report the Damage
In the DFW metroplex, we often have "hail seasons" where storms hit back-to-back. Some homeowners decide to wait until the season is over to file a claim, thinking they’ll just handle everything at once. This is a risky move. Most insurance policies have a "statute of limitations" or a specific window: often one year from the date of the loss: to file a claim.
The Mistake: If you wait 14 months after a major hail event to file, the insurance company can legally deny the claim based on the reporting delay. Furthermore, unrepaired damage can lead to secondary issues like mold or structural rot, which insurance may refuse to cover because you failed to mitigate the damage.
The Fix: If you suspect hail or wind damage, get an inspection immediately. Even if the damage seems minor, starting the paper trail early protects your right to a full settlement later. Whether you are in Fort Worth or Burleson, timing is everything.
4. Making Permanent Repairs Before the Adjuster Arrives
When a leak is dripping into your living room, the natural reaction is to fix it immediately. However, if you hire a handyman to replace a section of shingles or repair a flashing before the insurance adjuster sees it, you might be destroying the very evidence you need for your claim.
The Mistake: The insurance company needs to see the "original" damage to verify the cause of loss. If the damage is gone, they may claim there was never a problem to begin with.
The Fix: You should make temporary repairs to prevent further damage: this is actually a requirement in most policies. This means putting a tarp over a hole or stopping a leak with temporary sealant. Keep all receipts for materials and take photos of the damage before you cover it up. For emergency tarping and professional guidance, you can always contact us to ensure the repair is documented correctly for your claim.

5. Assuming the First Settlement Offer is Final
When the insurance adjuster sends you that first check, it can feel like a relief. However, that initial estimate is often a "starting point" rather than a final figure. Adjusters are often working on dozens of claims simultaneously after a major North Texas storm, and it is very common for them to miss specific line items.
The Mistake: Accepting the first check and signing off on the claim before a roofing professional has reviewed the scope of work. Common omissions include local building code requirements, high-quality underlayment, or necessary ventilation upgrades that are required for a roof replacement in DFW.
The Fix: Never assume the adjuster’s word is the final law. Have a roofing contractor who understands the insurance language review the estimate.
6. Going Solo During the Adjuster Meeting
Many homeowners feel they should be the only ones present when the insurance adjuster arrives to inspect the roof. While you certainly have the right to be there, you may not know what to look for or how to advocate for the structural integrity of your home.
The Mistake: Letting the adjuster inspect the roof alone. While most adjusters are professional, their job is to find the most cost-effective solution for the insurance company. They might overlook "bruising" on a shingle that indicates a hail strike, or ignore damage to the soft metal vents.
The Fix: Ask your roofing contractor to be present during the adjuster's inspection. We regularly meet adjusters on-site at homes across Midlothian and the wider DFW area. Having a professional on the roof with the adjuster ensures that every point of damage is seen, discussed, and documented in real-time. It’s about making sure the "playing field" is level.

7. Falling for "Storm Chasers" and Low-Ball Quotes
After a major storm, "storm chasers" often flood DFW neighborhoods. These are out-of-state contractors who follow storms, knock on doors, and offer to "waive your deductible" or provide a suspiciously low quote.
The Mistake: Hiring a contractor based solely on price or the promise of a "free" roof. Waiving a deductible is actually illegal in the state of Texas (Texas Business and Commerce Code § 701.002), and low-ball quotes often mean the contractor is cutting corners on materials or labor to make a profit.
The Fix: Work with a local, established company that has a physical presence in the community. Look at their gallery of work and check their reputation. At Texas Best Roofing Solutions, we pride ourselves on transparency. We won't cut corners because we know that a roof in North Texas needs to be built to last through the next storm, not just until the insurance check clears.

Why the Right Partner Matters
The insurance claim process doesn't have to be a battle. When you have the right information and a team that understands the technicalities of both roofing and insurance adjusting, the process becomes much smoother.
At Texas Best Roofing Solutions, we aren't just here to nail down shingles. We are here to be your advocate.
If you suspect your roof has been damaged by a recent storm, don't wait for a leak to tell you there's a problem. Take advantage of our expertise today.
Ready to get started?
- Schedule your Free Roof Inspection
- Learn more about our team and values
- Explore our service areas in DFW
Let us help you navigate your claim with confidence. We’ll handle the roof work, so you can focus on getting back to normal.
As a roofing contractor, Texas Best Roofing Solutions does not act as a public adjuster or negotiate insurance claims. The insurance company determines coverage under the policy.
Roof damage or a leak? Talk to Stan Short.
Call (817) 919-4310 or request a roof inspection.